Absa’s AgriTrends Spring 2026 report points to improving conditions in South Africa’s livestock industry following the 2024 drought and the disease outbreaks that disrupted production and trade during 2025 and 2026.
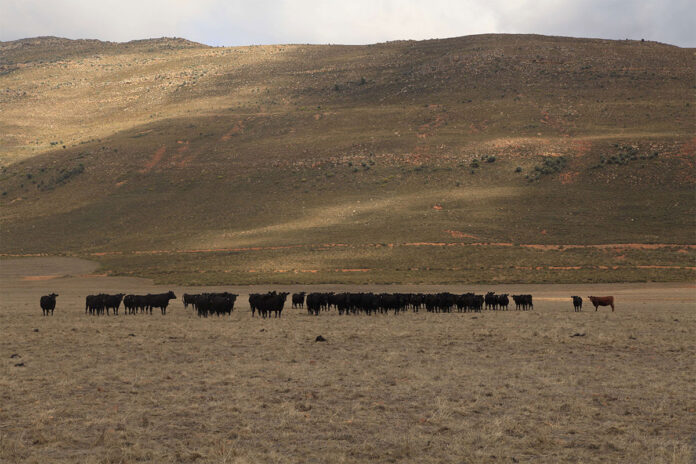
Favourable rainfall has improved grazing across key production regions, while abundant maize supplies and lower feed costs have supported producer margins. These conditions are giving cattle and sheep farmers an opportunity to rebuild breeding herds depleted or placed under pressure during the drought.
However, Jade Smith, agricultural economist at Absa, told Farmer’s Weekly that the recovery is having different effects across the meat industries. Cattle and sheep producers are retaining breeding animals rather than sending them to slaughter, limiting the immediate supply of beef, lamb, and mutton and supporting prices in parts of the red meat market.
The opposite trend is evident in pork and poultry. As disease-related disruptions ease, slaughter activity and production are recovering, increasing the amount of meat available and placing downward pressure on some producer prices.
She said that diseases, such as foot-and-mouth, African swine fever, and avian influenza, remained a central risk to the outlook, even when underlying production conditions were improving.
A potential El Niño event presents a further risk because it could reduce grain production and push maize prices higher. This would raise feeding costs for poultry and pork producers and put pressure on feedlot margins.
Smith nevertheless expects South Africa’s abundant maize supplies and comfortable carry-over stocks to provide some protection against short-term price increases.
Beef: Disease disrupts trade as producers rebuild herds
Foot-and-mouth disease (FMD) has disrupted South Africa’s beef recovery, restricting cattle movements and export access even as better grazing and lower feed costs improve production conditions.
The disruption was particularly severe in July, according to the report, when cattle slaughter numbers fell by 47% year on year. Across 2026 more broadly, slaughter volumes were 7,6% below 2024 and 2025 levels.
Beef export volumes fell by 50,2% in the first seven months of 2026 compared with the corresponding period in 2025.
Smith stressed that restoring export momentum, especially to countries like China where South African imports are still suspended, was imperative to support prices and heavily depended on effective disease control, veterinary protocols, traceability, and buyer confidence.
Disease restrictions, however, only partially explain the lower slaughter numbers. Smith pointed out that favourable rainfall has improved grazing, while lower maize prices have reduced feeding costs, allowing producers to retain cattle for longer and rebuild breeding herds.
Producer margins have also improved. The beef-to-maize ratio, which measures beef prices relative to maize costs, increased by 9,1% compared with 2025, largely because of cheaper feed. “Together with better grazing, this has given producers greater flexibility over when to market their animals,” Smith said.
These conditions have contributed to contrasting price movements. Weaner calf prices rose by 32,2% year on year in July as stronger feedlot demand coincided with reduced availability during herd rebuilding. Class C beef prices increased by 6,6% as producers retained breeding cows, limiting the number of cull animals marketed.
Class A beef prices, however, declined by 5,2%, due to improved supplies of feedlot cattle and softer demand for premium beef.
Looking ahead, Smith expects beef availability and slaughter throughput to improve through spring and summer as disease pressures ease, moderating the supply tightness that supported earlier carcass price peaks.
The report forecasts annual average Class A beef prices of R64,46/kg in 2026 and R65,12/kg in 2027, compared to R58,80/kg in 2025. Class C prices are forecast at R58,06/kg and R59,12/kg respectively, compared to R55,86/kg in 2025, and weaner prices averaging R43,48/kg and R45,22/kg, compared to R36,84/kg in 2025.
Beef price outlook
| Beef prices (R/kg) | 2025 average | 2026 forecast | 2027 forecast |
| Class A | 58,80 | 64,46 | 65,12 |
| Class C | 55,86 | 58,06 | 59,12 |
| Weaner calves | 36,84 | 43,48 | 45,22 |
Source: Absa AgriTrends Spring 2026.
Dairy: Milk production holds up despite FMD
South Africa’s dairy industry contributes to both milk production and beef supplies. Smith explained that older dairy cows generally enter the Class C beef market when culled, while younger animals, including infertile heifers, may enter the Class A or B markets. Dairy herd management decisions therefore influence the availability of animals for beef production.
FMD has put these herds under pressure, disrupting operations, reducing productivity and, in severe cases, forcing the premature culling of productive animals. Despite these challenges on affected farms, Absa reports that national milk production has remained stable and continued to record modest growth.
According to Smith, further milk production growth is expected in 2026, supported by improvements in herd management, productivity, and animal health. Effective disease surveillance, biosecurity, and rapid containment will remain essential to protecting productive herds.
Lamb and mutton: Flock rebuilding keeps supplies tight
Improved grazing conditions are helping South African sheep producers rebuild their flocks, but the retention of breeding animals is keeping slaughter supplies tight and supporting lamb and mutton prices.
Smith said that the national flock was already under pressure from years of drought, stock theft, and animal health challenges before the 2023/24 drought. Favourable rainfall during the 2025/26 summer has since improved veld conditions across key production regions, giving farmers an opportunity to rebuild numbers.
This recovery takes time to translate into increased meat production. As farmers retain breeding animals, fewer sheep reach the market, adding to the supply constraints caused by the longer-term decline in flock numbers. Lamb prices consequently increased by 5,5% year on year in July 2026, while mutton prices rose by 8,7%.
A similar rebuilding cycle is supporting international prices. Producers in Australia and New Zealand increased slaughter during the earlier drought as grazing deteriorated, reducing their breeding flocks. Improved conditions subsequently encouraged them to retain animals, tightening the supply of sheep meat available for export.
Rebuilding can take between two and four years, according to Smith, depending on seasonal conditions and the extent of earlier flock reductions. Longer-term changes in land use are also constraining recovery, with sheep production competing with dairy, forestry, and horticulture in New Zealand and other livestock enterprises in Australia.
However, stronger international prices do not translate directly into equivalent increases in South Africa. Unlike New Zealand’s export-oriented industry, the local sheep meat market depends largely on domestic demand, making household purchasing power a key influence on prices. Affordability pressures are therefore likely to limit further increases, even while supplies remain tight.
Smith expects domestic lamb and mutton prices to remain supported over the medium term. The number of animals marketed should gradually increase as flocks recover, although the rebuilding process will continue to constrain availability in the meantime.
The bank forecasts annual average Class A sheep meat prices of R105,59/kg in 2026 and R107,11/kg in 2027, compared to R102,88/kg in 2025. Class C prices are forecast at R80,09/kg and R83,89/kg respectively, compared to R74,03/kg in 2025, while feeder lamb prices are expected to average R50,01/kg and R52,03/kg, compared to R46,61/kg in 2025.
Lamb and mutton price outlook
| Sheep prices (R/kg) | 2025 average | 2026 forecast | 2027 forecast |
| Class A | 102,88 | 105,59 | 107,11 |
| Class C | 74,03 | 80,09 | 83,89 |
| Feeder lambs | 46,61 | 50,01 | 52,03 |
Source: Absa AgriTrends Spring 2026.
Pork: Recovering supplies ease price pressure
Unlike extensive cattle and sheep operations, intensive pig production depends on the regular movement of animals through the production chain, with limited scope to delay marketing finished pigs.
Outbreaks of foot-and-mouth disease and African swine fever did not materially reduce production capacity, but movement restrictions and tighter biosecurity disrupted deliveries to abattoirs.
The resulting temporary supply squeeze pushed porker and baconer prices to around R40/kg in the first quarter, compared with normal levels of about R32/kg, according to the report.
These record high prices made imported pork more competitive. Imports increased by 149% in the first five months of 2026 compared with the corresponding period in 2025, adding to domestic availability. Import volumes subsequently began to moderate as local production and slaughter activity recovered.
Improved domestic supplies, together with inventories accumulated during the disruption, eased market tightness and brought prices down. By July, porker prices were 6,8% below year-earlier levels, while baconer prices were marginally lower, declining by 0,1%. Absa interprets this correction as a return to a better-balanced market.
Smith expects pork prices to follow underlying supply and demand more closely through the remainder of 2026 and into 2027. Maintaining this stability will depend on effective biosecurity, disease surveillance, and the industry’s ability to keep animals moving through the production chain.
Despite the year-on-year declines recorded in July, Absa’s full-year forecasts remain above 2025 averages. Porker prices are forecast to average R35,55/kg in 2026 and R36,22/kg in 2027, compared with R34,80/kg in 2025. Baconer prices are forecast at R36,19/kg and R37,89/kg respectively, up from R34,08/kg in 2025.
Pork price outlook
| Pork prices (R/kg) | 2025 average | 2026 forecast | 2027 forecast |
| Porkers | 34,80 | 35,55 | 36,22 |
| Baconers | 34,08 | 36,19 | 37,89 |
The figures are annual average prices. Source: Absa AgriTrends Spring 2026.
Poultry: Lower feed costs support margins and output
Individually quick frozen (IQF) chicken prices declined by 1,1% year on year in July 2026 as stronger production increased supplies.
Lower maize prices have supported this expansion while improving producer margins. Feed accounts for about 70% of poultry production costs, making grain prices a major influence on profitability.
Smith said the sector entered 2026 in a stronger position after the severe avian influenza outbreak in 2023 and elevated feed costs in 2024. Improved surveillance, rapid responses, and stronger biosecurity also helped contain H5 highly pathogenic avian influenza outbreaks in 2026, limiting their impact on production.
Disease remains a threat, while a potential El Niño event could increase grain prices and erode the benefit of cheaper feed. Nevertheless, strong domestic maize supplies and comfortable carry-over stocks should provide some protection against short-term price shocks.
Absa forecasts annual average IQF chicken prices of R36,66/kg in 2026 and R37,34/kg in 2027. Frozen whole-bird prices are expected to average R34,97/kg and R35,62/kg respectively, while fresh whole-bird prices are forecast at R41,09/kg and R41,96/kg.
| Poultry prices (R/kg) | 2025 average | 2026 forecast | 2027 forecast |
| Frozen whole bird | 34,20 | 34,97 | 35,62 |
| Fresh whole bird | 39,80 | 41,09 | 41,96 |
| IQF chicken | 35,20 | 36,66 | 37,34 |
The figures are annual average prices. Source: Absa AgriTrends Spring 2026.