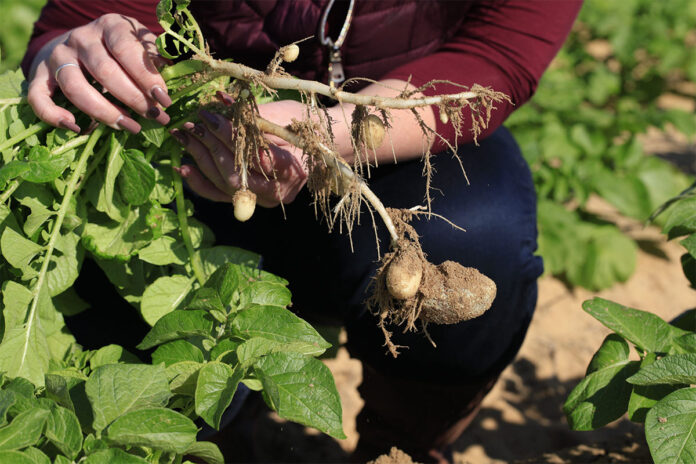
Potato volumes increased by 8% to 66,55 million 10kg bags by mid-season, while onion volumes rose 10% to 24,61 million bags. This placed potato deliveries 2,46 million bags above the five-year average and onions 1,81 million bags above their five-year average.
According to the report, the contrasting price response showed that higher supply alone did not determine market outcomes. The timing and distribution of produce entering the market, as well as the market’s ability to absorb it, also influenced prices.
Potato market takes strain
For potatoes, the additional supply came at the expense of market value. Absa estimated that the total value of sales represented on fresh produce markets fell by about 12%, from R3,69 billion in 2025 to R3,25 billion in 2026, despite the higher volume sold.
FP Coetzee, manager of information and regional services at Potatoes SA, told Farmer’s Weekly the decline could not simply be blamed on an overall increase in potatoes entering the market.
He explained that North West experienced an oversupply of large potatoes during the first half of the year, while some potatoes originally earmarked for processing were diverted to fresh produce markets due to internal issues.
“The result was a combination of higher overall volumes, poorer quality and an oversupply of a specific size category, all putting pressure on prices,” he said.
Absa noted that potato prices subsequently recovered during winter, with the average reaching R64,34 per 10kg bag, compared with a year-to-date average of R48,76.
Coetzee said prices were expected to have reached around R80/kg by now, as stock levels had declined from about 820 000 bags during most of the first half of the year to 688 000 bags for the past eight weeks.
Prices, nevertheless, were moving sideways. An abundance of large potatoes of poorer quality was again weighing on the market, with the percentage of Class 1 Potatoes accounting for only 70% of market supply, rather than rising above 80%.
Coetzee had furthermore observed a decline in the rate at which potatoes were moving through the market, possibly due to the large number of foreigners that left the country a few months ago.
Along with this, he suspected that direct marketing of table potatoes was increasing, which could partly explain the relatively low volumes being channelled through fresh produce markets.
Despite prices not rising as expected, Coetzee said the greater stability was positive for growers and buyers: “A more stable market reduces the risk associated with sharp price swings and could, in turn, reduce the need for buyers and retailers to build large risk margins into their pricing.”
Manage quality, not price
Coetzee said the answer for producers was not to chase prices, but to manage quality, sizing and stock more carefully.
Growers should ensure that potatoes were correctly sized and avoid flooding the market to the point where new deliveries competed with their own older stock. Delivering from Monday to Thursday could also help improve stock rotation and quality management.
He also urged producers selling directly to buyers to market responsibly.
If growers diverted their best-quality potatoes to direct buyers while sending lower-quality produce to fresh produce markets, this would still put pressure on market prices – and ultimately on their own direct-market returns, as these prices were derived from fresh produce market prices.
Coetzee’s advice was therefore for producers to focus on putting good-quality produce on the market and managing stock properly, rather than trying to chase prices.
Onions absorb higher volumes
Onions, meanwhile, have so far handled increased supply without the same price pressure.
The average onion price rose 8% to R72,34 per 10kg bag, from R66,93 in 2025, despite the 10% increase in volumes.
Absa said this suggested that the additional onion supply had so far been absorbed without creating the same imbalance seen in potatoes. It did not necessarily mean demand had increased sharply, but rather that available supply and demand had remained better aligned.
The regional supply mix also shifted considerably. North West onion deliveries were almost double those of the corresponding period in 2025, while Limpopo volumes increased 14,8%. Deliveries from the Free State and Northern Cape were slightly higher, while Sandveld volumes fell almost 20%.
According to Absa, these shifts mattered because the timing and scale of deliveries from individual production regions determined how much produce reached the market at any particular point.
The contrasting performance of potatoes and onions ultimately illustrated a broader challenge for vegetable growers, in that producing more does not necessarily mean earning more.
Quality, timing and the ability to manage additional supply were becoming increasingly important in determining whether higher output translated into sustainable returns.
For more information, view Absa’s AgriTrends 2026 Spring Edition.