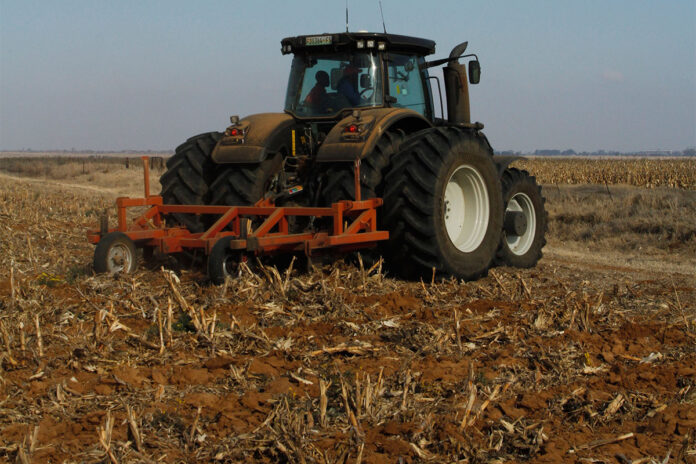
South African farmers who claim diesel refunds face a major administrative change: they must register afresh on a new digital system, even if they have claimed successfully under the existing VAT-linked scheme for years.
The South African Revenue Service (SARS) opened its Diesel Refund Registration System to users and sellers on eFiling on 21 September 2026. During its Diesel Refund Modernisation webinar on 18 September, officials stressed that no existing registration would migrate automatically. Until a farmer completes the new application, that business is effectively unregistered for the future claims system.
SARS is separating diesel refunds from VAT and building a digital chain linking the seller, buyer, production site, equipment, and qualifying activity. Registration and supplier-relationship management are available first; the user profile and claims functions will follow.
CURRENT VAT CLAIMS CONTINUE
The September launch covers registration, not claims. Farmers must continue submitting diesel refund claims through their VAT201 returns until SARS announces the implementation date of the standalone claims platform. Registering onto the new system does not stop or replace current VAT-linked claims.
The old and new arrangements will operate in parallel during the transition. Diesel used before the eventual implementation date will remain under the VAT-linked process, while diesel used from the announced cut-off date will be claimed on the new platform. SARS has not yet announced that date.
Because claims are subject to a two-year prescription period, records must be divided accurately at the cut-off date. Mixing transactions from the two regimes could cause duplicate, omitted or incorrectly submitted litres.
SUPPLIERS MUST REGISTER TOO
The biggest operational risk is that a farmer’s ability to claim will depend partly on the supplier’s compliance. Every diesel seller serving refund users must register and receive a diesel tax reference number. The farmer uses that number to request an electronic relationship on eFiling, which the supplier must confirm.
When the claims function opens, farmers will have to select the seller connected to each purchase. If a supplier has not registered, it will not appear on the system and the farmer may be unable to include those litres in the claim, regardless of the quality of the invoice or fuel-use records.
SARS said there would be no public list of registered sellers. Farmers must approach every wholesaler, co-operative, distributor, depot, or filling station they use, confirm registration, and obtain the diesel tax reference number. A filling station needs to register only if it supplies diesel to users participating in the refund scheme.
WHO QUALIFIES UNDER THE NEW SYSTEM
Qualifying activities are grouped into eight categories: agriculture, fishing, mining on land, offshore mining, offshore shipping, harbour shipping, rail freight transport, and electricity generation. Farming and forestry are combined under agriculture, and applicants may select more than one category where applicable.
The concession remains restricted to prescribed primary-production activities. Secondary agricultural operations, such as fruit packing and fruit-juice manufacturing, do not qualify merely because they are connected to a farm. Mixed businesses must separate diesel used in primary production from processing, packing, private use, and other excluded activities.
Contractors who purchase diesel and use it to perform qualifying work for someone else will be able to register under the revised framework. They cannot yet claim under the new provisions; that right begins only when the claims system and related legislation take effect.
The contractor change creates a double-claim risk. If the farmer supplies the diesel, records must show how it was issued and used; if the contractor buys it, the contractor may be the claimant. Agreements should specify who buys the fuel, keeps the records, and submits the claim.
HOW TO REGISTER
Applications may be submitted through eFiling or with assistance at the SARS branch. SARS recommend eFiling because it is faster and because the supplier-relationship function is available only online.
Before applying, taxpayers should ensure their SARS profiles are matched, validated and current. An unvalidated profile may prevent access to diesel functionality. Addresses, banking details, and representative information intended for the application should first be updated under the taxpayer’s registered particulars.
The applicant uses the RAV01 form to add diesel refunds as a tax product and selects either diesel refund user or diesel refund seller. A single application cannot cover both roles. After submission, SARS issues a case number, acknowledgement and formal request listing the supporting documents required for the relevant category.
Once approved, the applicant receives a diesel tax reference number and must activate the diesel refund tax type on eFiling before the diesel dashboard and relationship tools become visible. SARS has proposed a turnaround time of up to 21 business days for complete applications, although high initial volumes could cause delays.
Common problems include unmatched eFiling profiles, outdated addresses, unregistered bank details, selection of the wrong applicant type, omitted categories, missing documents, registration of the wrong legal entity and failure to activate the tax type after approval. Farmers should retain the case number and monitor SARS correspondence.
ONE ENTITY MAY COVER SEVERAL FARMS
A single legal entity operating several farms needs one user registration, but every location where qualifying activity takes place will eventually have to be disclosed in the user profile. Adjacent properties may be covered by one site plan, while separate farms may require individual plans or additional information.
Where a farming operation is divided among companies, trusts, partnerships or individuals, each entity that purchases and uses qualifying diesel may require its own registration. Operating under one farm name or management structure does not automatically make separate entities one diesel refund user.
Farmers should check that the entity named on the invoice is the entity paying for the diesel, conducting the qualifying activity, and submitting the claim. An invoice issued to one company but used to support another entity’s claim could create difficulties during verification or audit.
RECORDS REMAIN THE FOUNDATION
Registration does not guarantee a refund. SARS may still examine whether the diesel was bought and used for a prescribed activity. Invoices, proof of payment, delivery notes, logbooks, storage records, equipment details and the connection between the fuel and the farming task remain essential.
Bulk tanks and mobile bowsers need tight control. Farmers should be able to reconcile opening stock plus purchases, less closing stock, with fuel issued to qualifying activities, non-qualifying activities, and recorded losses. Where several farms or entities draw from a shared tank, each issue should be allocated to the correct claimant.
Fuel moved from a main tank into a bowser has not yet been proved to be a qualifying use. The records should follow the litres from supplier delivery to the main tank, bowser, machine, and specific activity. Fuel cards, electronic pumps, operator PINs, and equipment-level records can strengthen this audit trail.
An equipment register should identify each tractor, harvester, pump, truck, or generator, including its serial, fleet or registration number, ownership or lease status, location, main activity and logbook or telematics reference. The register should be updated when machinery is acquired, transferred, hired, or sold.
Farm employees also need training. Entries such as ‘tractor’ or ‘general farm work’ may not establish eligibility. Records should identify the date, litres, machine, operator, farm or field, specific task and, where practical, the odometer or hour-meter reading.
GREY AREAS STILL NEED GUIDANCE
SARS did not settle whether GPS and telematics data will replace manual logbooks. Farmers should retain these digital records but should not assume that they remove the need for other evidence.
Generator diesel does not qualify merely because the unit is on a farm. Where one generator supplies production infrastructure and non-qualifying loads, the farmer will need a reasonable allocation method. SARS did not provide final guidance on generators or forklifts.
Evaporation, spills, meter tolerances, leaks and theft can explain differences between fuel bought and fuel recorded as used, but these losses should be documented when they occur. Theft should be supported by an incident report and, where relevant, a police case number.
CASH FLOW IS AT STAKE
Diesel refunds represent meaningful working capital for mechanised operations during planting, spraying, irrigation and harvesting. An incomplete application, unregistered supplier or unconfirmed relationship could delay a claim even when the diesel itself was used correctly.
Farmers should also distinguish between 100% eligible use and a refund of 100% of the diesel price. From 1 April 2026, qualifying on-land primary producers may calculate the applicable refund on 100% of eligible diesel use rather than the previous 80%. The concession still refunds specified levy components, not the full fuel price.
Working-capital forecasts should allow for transition delays. Farmers should monitor registration progress, supplier approvals, and document requests rather than assume payment will arrive on the usual timetable.
ACTION CHECKLIST FOR FARMERS
Farmers who claim or intend to claim diesel refunds should:
- Confirm that the correct eFiling profile is matched and validated.
- Update registered addresses, banking details, and representative information.
- Apply as a diesel refund user and retain the SARS case number.
- Upload every supporting document requested by SARS.
- Activate the diesel refund tax type after approval.
- List every business from which qualifying diesel is purchased.
- Ask each supplier to register and provide its diesel tax reference number.
- Request and confirm the electronic supplier relationships on eFiling.
- Review contracts with machinery operators and agricultural contractors.
- Compile farm, site, storage, and equipment information for the user profile.
- Reconcile purchases, tank movements, equipment use and closing stock monthly.
- Continue submitting existing claims through VAT201 until SARS announces the changeover.
WHAT REMAINS UNCLEAR
SARS still needs to clarify the exact evidence required for qualifying use; whether telematics may replace or only supplement logbooks; the treatment of shared tanks, rented machinery and transfers between related entities; and how mixed qualifying and non-qualifying machine use must be allocated.
Further guidance is needed on purchases from a seller whose registration is suspended after the sale, invoice corrections and credit notes, the time suppliers must approve relationship requests and the process where a claim fails because of mismatched supplier data.
PREPARE BEFORE THE CLAIMS PLATFORM OPENS
The registration period gives farmers time to correct tax profiles, involve suppliers and improve fuel controls before the new claims platform becomes compulsory. This should be treated as a farm-management and cash-flow project, not merely as an accounting task completed at the end of a VAT period.
The immediate priorities are to register the correct legal entity, ensure every supplier is registered and linked, and make certain that every qualifying litre can be traced from invoice to storage, machine, and farming activity. Farmers who do this early will be far better placed to protect their refunds when the new claims system is switched on.
This article is based on the SARS Diesel Refund Modernisation webinar of 18 September 2026. The full video of the webinar can be watched at Diesel Refund Registration Webinar.